
Reasons to choose the Bitsa card: updated 2026 guide
Choosing a bank card in 2026 means navigating dozens of options: neobank cards, traditional prepaid, cards linked to crypto exchanges, niche fintech cards. The Bitsa card occupies a specific space that others don’t usually cover: prepaid with associated IBAN, without linked bank account, with cryptocurrency top-up and full operation from an app.
This guide covers the concrete reasons why Bitsa fits certain user profiles, how the product works and how it’s requested.
8 concrete reasons to choose Bitsa
1. No linked bank account required. Bitsa is requested, activated and works without needing an account at a traditional bank. This is useful for someone who just moved and hasn’t opened a local account yet, for someone who prefers not to link their movements to their main bank, or for someone with difficulties accessing the traditional banking system.
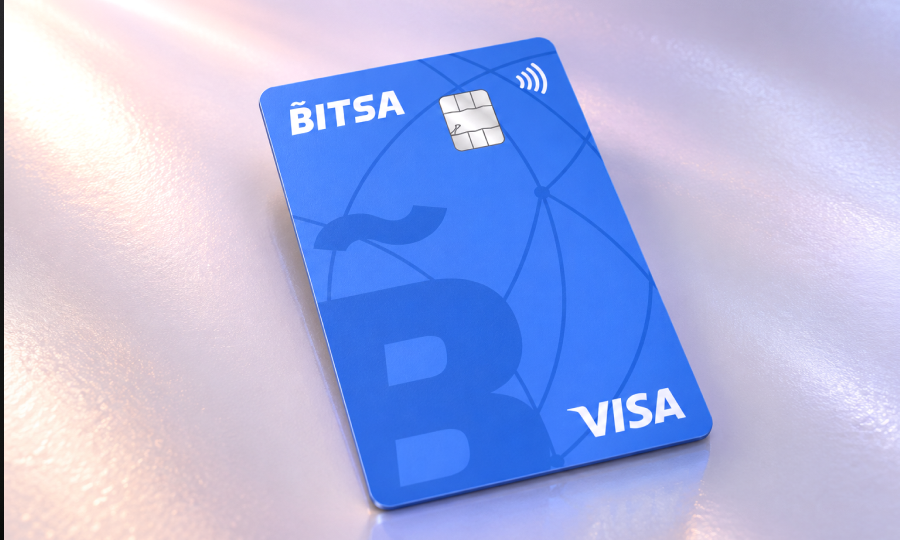
2. Free virtual card from day one. The basic plan (Free) includes a virtual card at no cost, issued immediately after completing registration and identity verification. It’s a complete Visa card, usable at any online merchant that accepts Visa, with valid details and standard operation.
3. Associated IBAN to receive transfers. Each Bitsa card carries an associated IBAN that allows receiving SEPA transfers from any payer: clients, employers, platforms, family. Funds arrive to the card balance and remain available to spend. SEPA transfers take between 24 and 72 business hours.
4. Cryptocurrency top-up. Bitsa accepts direct top-up from several cryptocurrencies (Bitcoin, Ethereum, USDT, BAT and others) without needing to convert to euros previously on a centralised exchange. It’s a practical route for those who receive crypto payments: Web3 project freelancers, content creators on decentralised platforms, digital nomads paid in tokens. A critical detail: the blockchain address for the top-up changes with every transaction and must not be reused.
5. International use without surprises. Being a complete Visa card, it works in any country where Visa is accepted. Purchases at international merchants apply the standard Visa exchange rate.
6. Multiple simultaneous cards by plan. Bitsa offers three plans with different numbers of active cards. The Free plan allows one virtual and one physical card. The Move plan allows up to three virtual and two physical. The Pro plan allows up to four virtual and four physical. The utility of having several simultaneous cards is concrete: separating subscriptions, travel expenses, risky online purchases or family management.
7. Instant Bitsa-to-Bitsa transfers. Between Bitsa users, transfers are instant and free. They’re done using the associated phone number or a unique code generated from the app. Useful for splitting expenses between international groups of friends or for transferring balance to family members who also use Bitsa.
8. Full control from the app. All account management is done from the Bitsa app: card requests, top-ups, transfers, balance check, temporary blocking, PIN change, hiding cards not in use. There’s no complementary web panel; mobile is the only entry point.
How Bitsa plans work
Bitsa operates with three plans that differ mainly by the number of simultaneously active cards.
- Free. 1 virtual card + 1 physical card.
- Move. 3 virtual cards + 2 physical cards. Focused on those who need to separate more expenses.
- Pro. 4 virtual cards + 4 physical cards. For professional use or management of multiple flows.
Virtual cards don’t allow ATM cash withdrawal. Physical cards do, after activation with back-of-card details and PIN setup. Updated information on plans, limits and commissions is available at the official Bitsa support centre.
How to request a Bitsa card
The complete process is done from the app.
- Download the Bitsa app (Android or iOS).
- Register account with email and phone.
- Verify identity with passport or ID (18+ only).
- Choose plan.
- Activate the virtual card (issued immediately after verification).
- Request physical card if the plan includes it. The physical card arrives by post and is activated by entering the back-of-card details.
- Top up the card with the preferred method: SEPA transfer, cryptocurrencies, voucher or transfer from another Bitsa user.
For more detail on top-up methods, the specific article on Bitsa prepaid card covers general functioning.
Which profiles it fits best
Bitsa isn’t a card for everyone. It fits especially well in these cases.
Frequent travellers. Separate card for travel expenses without exposing the main card, international use at any Visa merchant, and instant transfers between travellers in the same group if everyone uses Bitsa.
Freelancers and remote workers. IBAN to receive payments from international clients, crypto top-up for those who invoice in tokens, card separated from the main bank account for professional expenses.
Digital nomads. Combination of IBAN, crypto top-up, global use and app management covers the typical needs of those who live between countries. The article on prepaid crypto cards for digital nomads goes deeper into this use.
Sensitive online purchases. Those who buy in small stores, international marketplaces or platforms where they don’t want to expose main card details.
Recent arrivals to Europe. Practical alternative while completing the local bank account opening process.
Young adults starting to manage money. Those over 18 who want to start managing their finances without opening a full bank account.
Cryptocurrency savers. The programmed savings service (with minimum amount from 6 € in daily, weekly, monthly or annual frequency) allows regularly buying crypto from the Bitsa balance.
Frequently asked questions about the Bitsa card
How much does the Bitsa card cost?
The Free plan has no base cost. The Move and Pro plans have monthly fees detailed in the plans section of the app. Physical cards usually have a one-time issuance cost. Check the updated breakdown in the app or at the support centre.
Can I receive my salary on Bitsa?
Yes. The card has an associated IBAN that allows receiving SEPA transfers, including salaries. Funds are credited as usable balance on the card.
What happens if I send the wrong crypto to my Bitsa?
Recovery of funds sent by mistake (incorrect cryptocurrency or old address) requires specific handling and has a minimum cost of 10 % of the amount or 500 €, whichever is greater. It’s critical to verify you’re sending the correct cryptocurrency and to the address generated at the moment.
Can I withdraw cash from ATMs with Bitsa?
Yes, with the physical card. The virtual one doesn’t allow cash withdrawal. When activating the physical card and setting up PIN, it works at any ATM that accepts Visa, with the usual ATM withdrawal commissions.
Does Bitsa work outside the European Union?
Yes. As Visa, it works globally at any merchant or ATM that accepts Visa. International purchases apply the Visa exchange rate of the day.
Is it safe to use Bitsa for online purchases?
Yes. The card has standard security protocols for online payments (Visa Secure / 3D Secure) and the possibility of generating additional virtual cards according to the plan allows isolating specific purchases. If you detect unauthorised activity, you can block the card instantly from the app.